


The AI Chip Revolution Wouldn’t Be Possible Without This Company
The AI Chip Revolution Wouldn’t Be Possible Without This Company
Vandita JadejaSat, October 3, 2026 at 3:30 PM UTC
0
ShutterstockQuick Read -
TSMC earns a BUY rating with a $532 price target, implying 17% upside, as net income surged 77% yet shares trade at just 22x forward earnings.
TSMC trades cheaper than NVIDIA (25x) and ASML (29x) despite faster revenue growth of 36% year over year.
The 2nm node launch and $265 billion Arizona expansion anchor a bull case of $621, while margin compression and Taiwan tensions define the bear case.
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
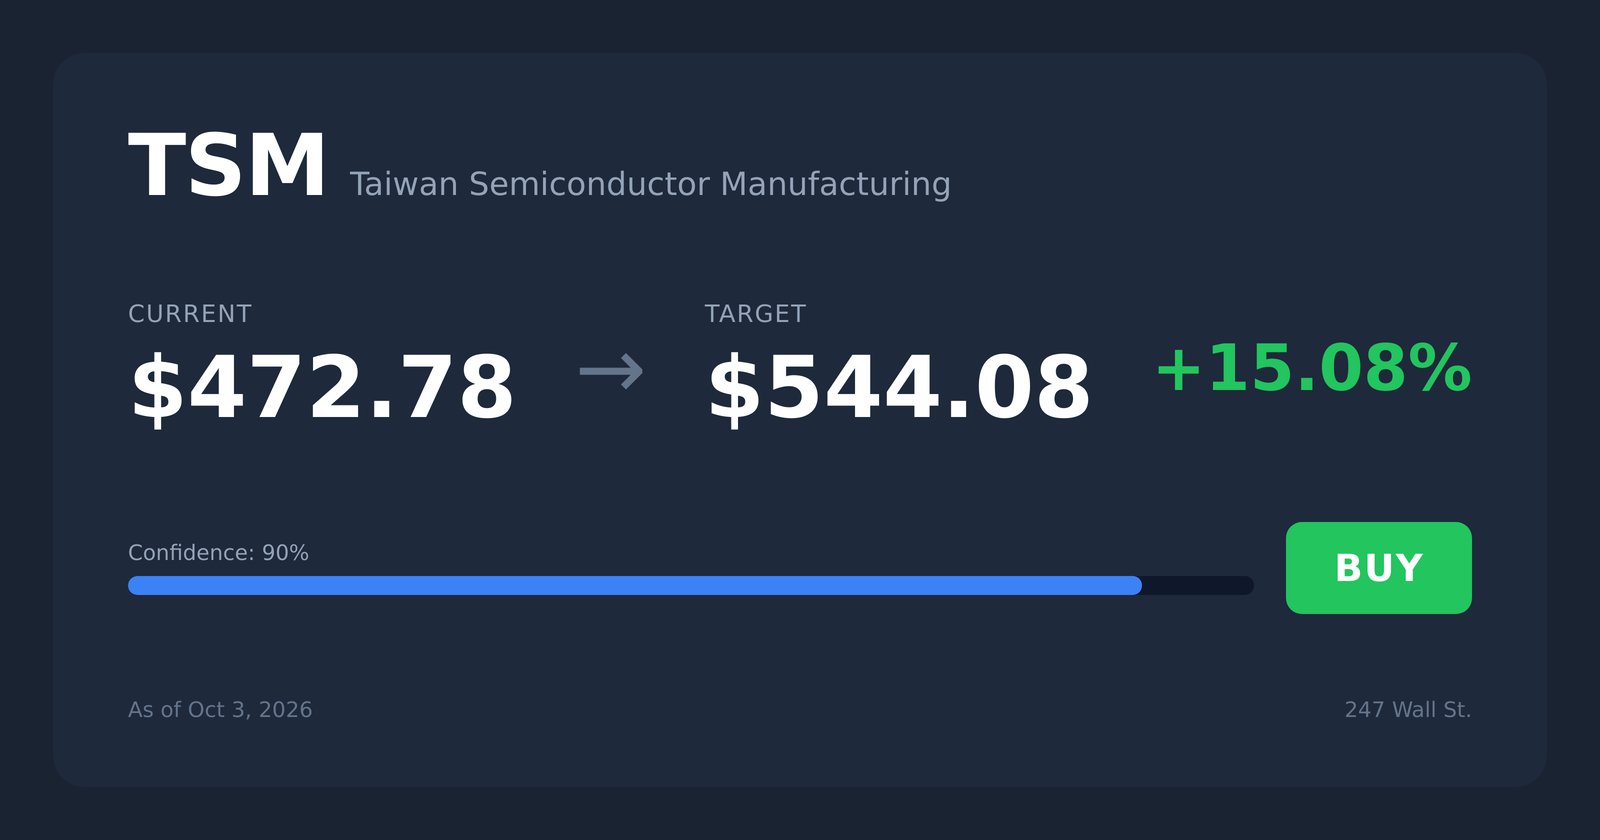
The 24/7 Wall St. price target for Taiwan Semiconductor Manufacturing (NYSE:TSM) is $531.86 over the next 12 months. This points to 16.53% upside from the current $456.41. Our model rates TSMC a buy with high confidence.
Metric
Value
Current Price
$456.41
Price Target from 24/7 Wall St.
$531.86
Upside/Downside
16.53%
Recommendation
Confidence Level
90%
TSM Price Target — 24/7 Wall St.
TSMC makes the chips inside nearly every major AI accelerator, and its results show it. High-performance computing rose 20% quarter over quarter to 66% of Q2 revenue.
Management now expects 2026 revenue growth slightly above 40% in USD terms, up from close to 30% in January. Net income grew 77.4%, yet the stock trades at just 22x forward earnings.
Shares Up 51% in 2026 as 2nm Production Begins
TSM has gained 2.19% over the past week, 10.17% over the past month and 51.32% year to date. Shares sit about 4.5% below the 52-week high of $477.71 and roughly 73% above the low of $264.34.
Q2 EPS of $4.31 beat the $3.87 consensus. TSMC has topped estimates in every quarter going back to early 2023. Revenue rose 36% to $40.20 billion, and 2nm launched at 3% of wafer revenue. August sales climbed 53.3% year over year. TSMC also raised its planned Arizona investment to $265 billion, and Barron's reports it could spend even more.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
TSM Price Scenario — 24/7 Wall St.Why Bulls See a Path to $620
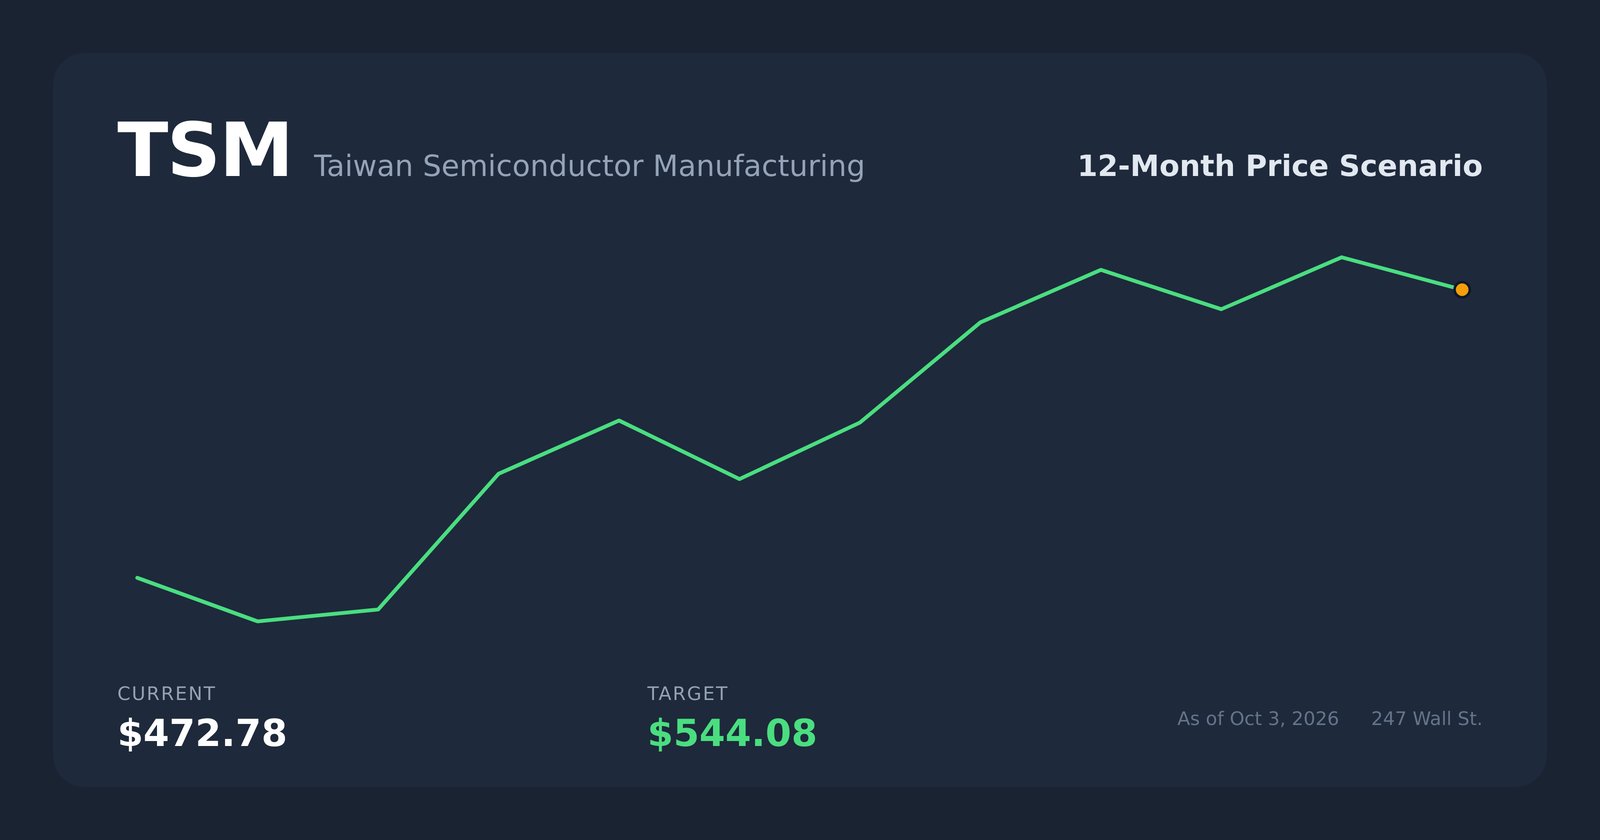
The bull case hits $620.74, a 36.01% gain. The 2nm ramp drives this, with A14 entering production in 2027 offering 10% to 15% speed improvement over N2. Advanced packaging remains tight, supporting pricing power.
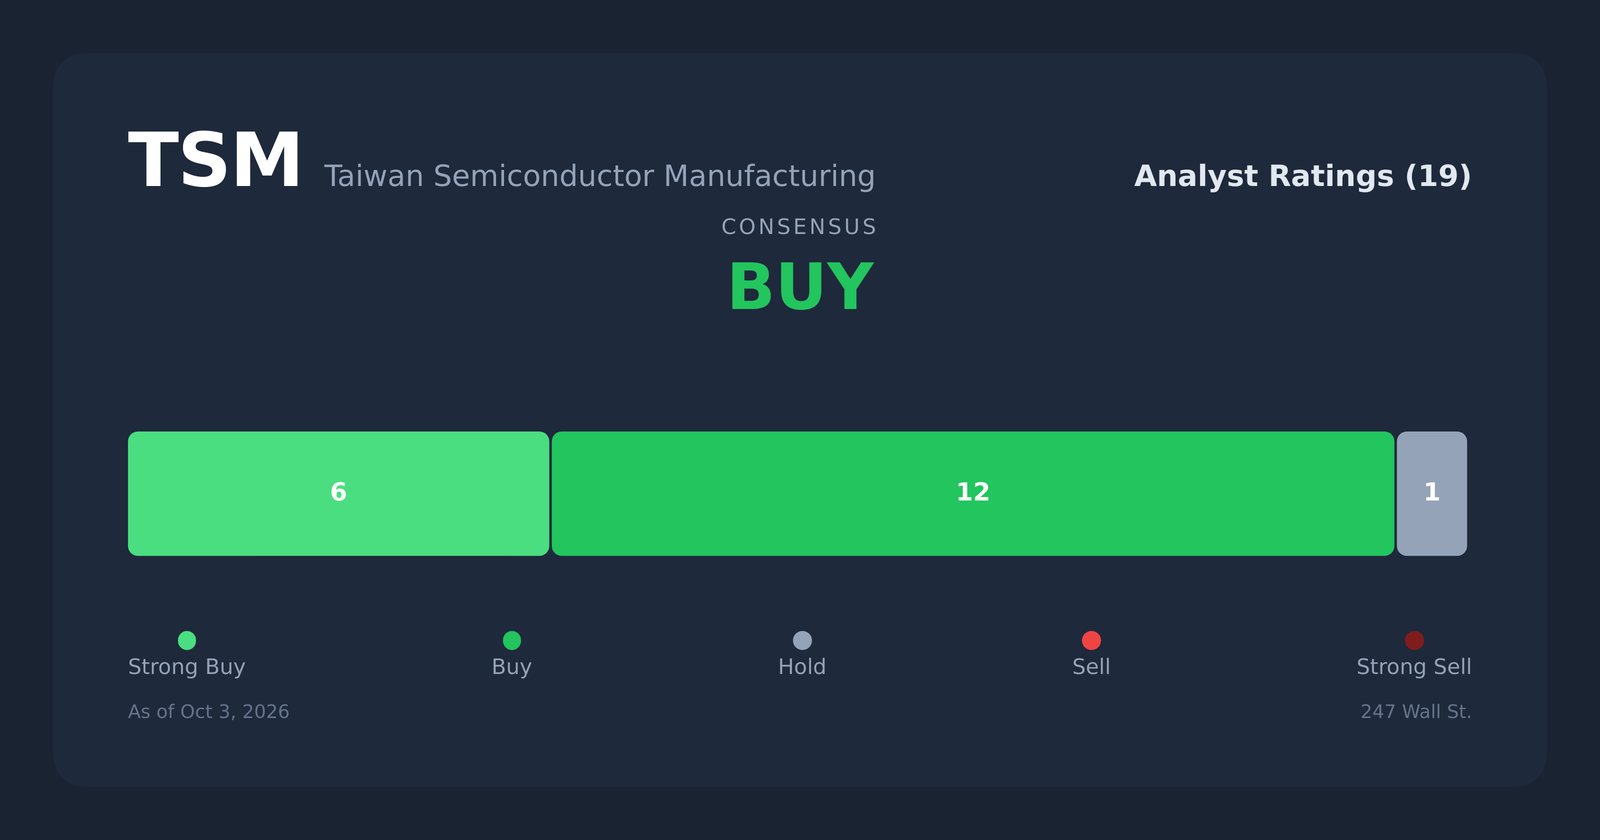
Management said "our conviction in the multi-year AI megatrend remains very high." Wall Street agrees: 6 strong buy and 12 buy ratings against one hold, with a consensus target of $552.26.
Advertisement
TSM Analyst Ratings — 24/7 Wall St.Margin Dilution and Taiwan Risk Could Stall Gains
The downside case is $443.67, or -2.79%. The 2nm ramp reduces gross margin by 3 to 4 percentage points, with overseas fabs adding more. The 2026 capital budget is $60 billion to $64 billion. Taiwan-China tensions and US export controls present risks.
Even the low end of Q3 gross margin guidance, 65%, is well above the long-term 56%+ target. Much margin pressure comes from capacity customers are asking for.
TSMC Trades Cheaper Than Its Biggest Customer
Company
Forward P/E
Quarterly Revenue Growth (YoY)
22x
36.0%
25x
105.9%
Intel
63x
25.4%
29x
21.3%
NVIDIA (NASDAQ:NVDA) is TSMC's biggest advanced-node customer and trades at a higher multiple, but its growth flows into TSMC's wafer orders.
Intel (NASDAQ:INTC) trades at 63x forward earnings despite trailing EPS of -$2.09.
ASML (NASDAQ:ASML) supplies the EUV tools TSMC needs yet trades at a higher multiple despite slower growth. At our target, TSMC would trade near 26x forward EPS, below ASML. The target looks reasonable against peers.
TSMC's Valuation Edge Supports the Upside Case
Our $531.86 target earns a buy rating and 90% confidence. TSMC's lower valuation versus dependent companies weighs in its favor. Key signals to monitor include whether 2nm yields keep Q3 gross margin within guidance, along with any rise in cross-strait tensions or cuts to hyperscaler AI spending.
The same expansion feeding TSMC's order book is also raised the power, cooling, and networking suppliers we profiled in a free report on seven AI infrastructure stocks that aren't chipmakers. On balance, upside outweighs risks.
TSMC Price Prediction 2026-2030
Our model projects where TSMC could trade if current trends hold:
Year
Price Target from 24/7 Wall St.
2026
$476.98
2027
$533.34
2028
$591.67
2029
$663.10
2030
$715.75
Released: The Definitive Guide to Retirement Income
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
